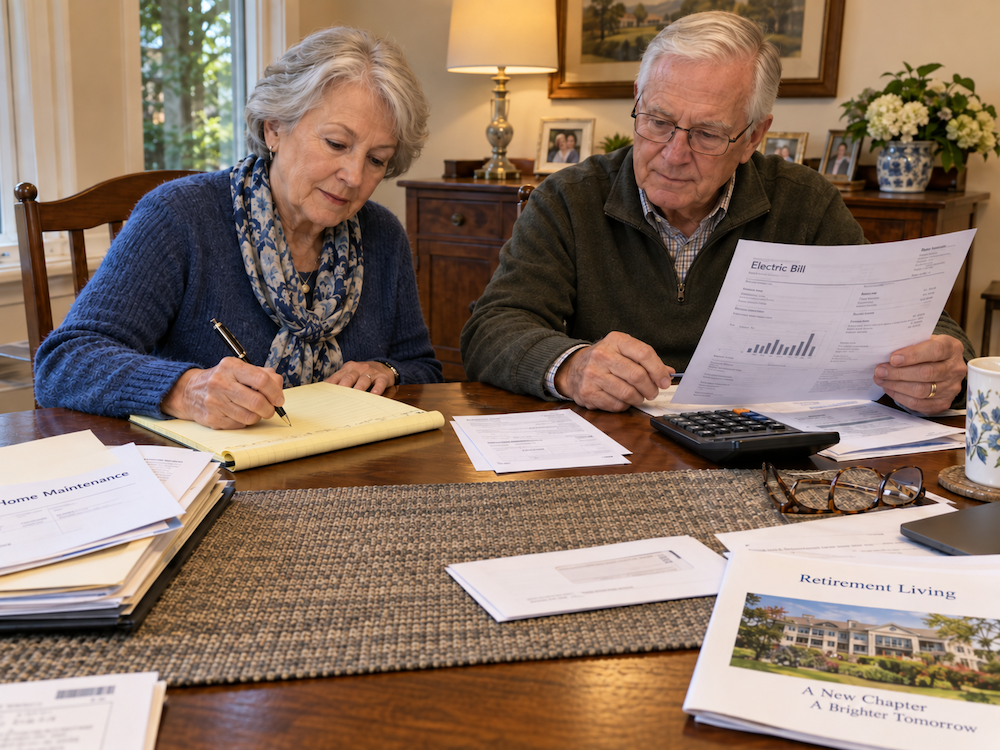
For many older adults, the decision to move to a retirement community isn't simply about where they want to live. It's also a financial decision.
At first glance, remaining in a home you've owned for years may appear to be the less expensive option, especially if your mortgage is paid off. By comparison, the monthly fee at an independent living or retirement community can look substantial. But comparing only your mortgage payment with the monthly cost of a retirement community doesn't tell the whole story.
Your current home has many expenses beyond the mortgage. A retirement community, meanwhile, may include services and amenities you currently pay for separately.
To make a meaningful comparison, it's helpful to look at your total monthly and annual cost of living in each situation.
What does it really cost to stay in your home?
Even when a home is mortgage-free, it isn't free to own. Start by adding up all the expenses required to maintain your current lifestyle. When calculating your monthly cost of staying home, divide these annual expenses by 12 so they can be compared more easily with a retirement community's monthly fee.
Property taxes and homeowners' insurance
Property taxes can represent a significant annual expense, and homeowners' insurance premiums may increase over time. Depending on where you live, you may also have additional insurance expenses for flooding, wind, or other risks.
Home maintenance and repairs
Every home requires ongoing maintenance. You may regularly pay for services such as lawn care, landscaping, and pest control. You probably also encounter other expected and unexpected expenses like HVAC maintenance, plumbing and electrical repairs, gutter cleaning, pressure washing, major appliance repairs or replacement, exterior painting, and roof repairs.
Some years may be inexpensive, while others may include a major expense such as replacing a roof, air conditioner, water heater, or refrigerator. Even if a large repair isn't needed today, budgeting for future repairs provides a more realistic picture of the long-term cost of owning your home.
Utilities expenses
Consider all the monthly services required to operate your home, including electricity, natural gas, water, sewer, trash collection, internet, television, and other utilities.
Some retirement communities include certain utilities in their monthly fee, which can make household expenses simpler and more predictable.
Food and dining
How much are you currently spending on groceries, restaurant meals, takeout, and food delivery? Depending on the community, retirement living may include a certain number of meals each day or month. Some communities offer several dining venues, cafés, or flexible dining plans.
When comparing costs, subtract the food expenses that could be replaced by your community's dining program rather than viewing the retirement community's monthly fee as an entirely new expense.
Entertainment, fitness, and social activities
Your current lifestyle may include memberships and activities such as a gym, fitness classes, clubs, concerts, lectures, movies, hobbies, or community events. Retirement communities frequently offer many of these activities as part of their lifestyle programming.
You may find fitness centers, swimming pools, art studios, libraries, walking clubs, educational programs, live entertainment, outings, social events, and other activities available without paying for each one separately.
These amenities have financial value, but they can also provide something harder to put a price on: convenient opportunities to stay active and connected with other people.
The cost of future home modifications
Your current home may work perfectly for you today, but it's worth considering whether it will continue to meet your needs in the years ahead as you age. A home with stairs, narrow hallways, bathrooms without grab bars, or difficult-to-access entrances may eventually require modifications.
Potential projects could include installing grab bars, remodeling a bathroom, widening narrow doorways, adding improved lighting, installing a stair lift, or relocating laundry facilities to the main floor. You may never need some of these changes, but including possible future modifications in your planning can help you make a more complete comparison.
Don't forget the value of your time
Maintaining a house requires not only money but time and energy too. There are repairs to arrange, contractors to call, yards to maintain, rooms to clean, packages to receive, bills to manage, and seasonal projects to complete.
You may enjoy taking care of your home today, but there may come a day when you feel that your house is taking care of your schedule. Moving to a retirement community can transfer many of those responsibilities to someone else.
Comparing your current expenses with a retirement community
One of the simplest ways to evaluate the decision is to create a list with two columns: “Staying Home” and “Retirement Community.”
Under "Staying Home," calculate your average monthly expenses for:
- Housing
- property taxes
- Homeowners’ insurance
- Maintenance
- Utilities (electric, gas, water, sewer, cable, etc.)
- Security system
- Meals
- Housekeeping
- Entertainment
- Fitness center memberships
- Other regular costs
Then compare that total with the retirement community's monthly fee.
Ask the community exactly what's included. Depending on the community, the monthly fee might cover services such as:
- Apartment or cottage rent
- Property maintenance
- Landscaping
- Some or all utilities
- Some or all meals
- Housekeeping
- Scheduled transportation
- Fitness programs
- Social activities
- Educational programs
- Entertainment
- Security or emergency response systems
Consider one-time moving costs, too
Moving also involves expenses that aren't part of your normal monthly budget. These may include moving services, downsizing assistance, packing, storage, new furniture, deposits, entrance fees, or other community-specific charges.
If you're selling your current home, there may also be real estate commissions, repairs, staging expenses, closing costs, and other costs associated with preparing and selling the property.
Ask prospective retirement communities to explain all one-time and recurring fees so you can compare your options accurately.
What happens to the equity in your home?
For homeowners, the house may be one of their largest financial assets. Selling it could make substantial home equity available for retirement savings, investments, travel, future healthcare expenses, or other priorities. Of course, selling a home also means giving up potential future appreciation in that property.
Because everyone's financial circumstances are different, it can be helpful to discuss the implications with a financial advisor or other qualified professional before making a major housing decision.
Look beyond today's costs
It's natural to focus on what each option costs right now. But this is also a decision about the next five, ten, or fifteen years. Think about questions such as:
- Will maintaining the house become more expensive?
- Will you still want to handle home maintenance?
- How important will convenient transportation become?
- Would you value having meals, activities, and fitness opportunities nearby?
- Would living closer to other people make it easier to maintain an active social life?
- Is your current home designed to support you comfortably as you grow older?
The answers can help you evaluate not only what each choice costs today, but also which living arrangement may better support the lifestyle you want in the future.
The lowest price isn't always the best value
There isn't one financial answer that's right for everyone. For some older adults, remaining at home will clearly cost less. For others, once property taxes, repairs, maintenance, utilities, transportation, food, housekeeping, and entertainment are considered, the difference between staying home and moving to a retirement community may be smaller than expected.
The key is to compare total cost with total value. Instead of asking only, "How much does a retirement community cost?"consider asking a broader question: “What am I spending to maintain my current lifestyle, and what would I receive for the money I spend in a retirement community?” Putting those numbers side by side can make the decision much clearer and help you choose the option that best fits your finances, priorities, and vision for retirement.
Is Independence Hill Retirement Resort a good choice for you? Experience it for yourself
See Independence Hill Retirement Resort in San Antonio for yourself: schedule your tour today. Have questions? We’re here to help! Call (210) 615-4000 to talk with a knowledgeable and experienced team member.